Amazon Q3 Preview: AWS, a $220 Billion Capex Plan and a $110 Billion Anthropic Deal
AWS growth hit 37% in Q2, but cash capex has outrun AWS revenue for five straight quarters. Anthropic's S-1 shows the other side of Amazon's biggest AI bet: a $110 billion compute commitment and notes that convert at the IPO.
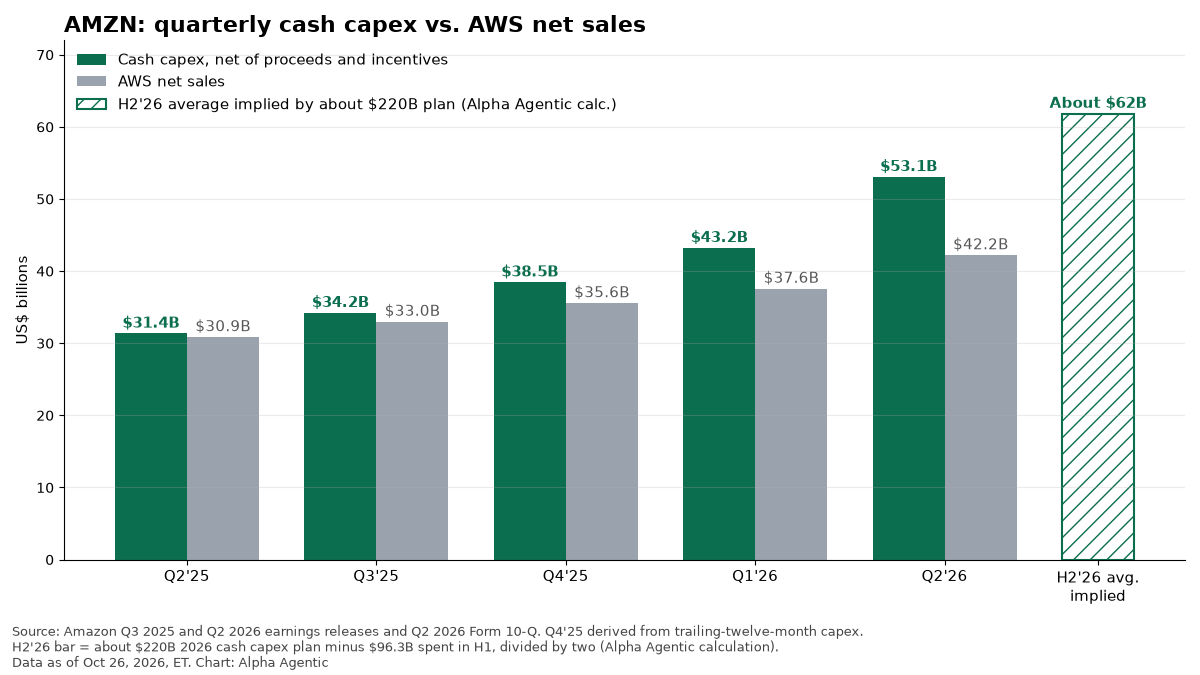
Amazon (NASDAQ: AMZN) has to show that AWS revenue is catching up with its spending. AWS growth accelerated to 37% in the second quarter, its fastest in 18 quarters. But cash capex has exceeded AWS revenue in each of the past five quarters, and trailing free cash flow has turned negative.
Anthropic's IPO filing adds a second test. It shows the customer side of Amazon's largest AI relationship: a $110 billion minimum compute commitment to AWS, and convertible notes that Amazon carries at $97.9 billion and that convert at the IPO.
Amazon holds its call at 5:00 p.m. ET on Thursday, Oct. 29. Analysts expect AWS revenue to grow 38.2% from a year earlier, according to Visible Alpha data reported by Reuters on Oct. 27.
Key numbers
AWS revenue: $42.2 billion in Q2 2026, up 37% from $30.9 billion in Q2 2025.
Q3 2026 AWS growth consensus: 38.2% from Q3 2025, against 37% in Q2 2026, per Visible Alpha data reported by Reuters on Oct. 27.
Cash capex: $53.1 billion in Q2 2026, against AWS revenue of $42.2 billion in the same quarter.
2026 cash capex plan: about $220 billion, raised on the Q2 2026 call from about $200 billion.
Trailing free cash flow: an outflow of $7.6 billion for the 12 months to June 2026, against an inflow of $18.2 billion for the 12 months to June 2025.
Anthropic convertible notes: about $97.9 billion of estimated fair value on Amazon's books at June 30, 2026, against $6.2 billion of principal.
Where Amazon Stands
In the second quarter of 2026, Amazon reported net sales of $200.6 billion, AWS revenue of $42.2 billion and cash capex of $53.1 billion, and its diluted EPS was $5.75.
| AMZN, $ millions | Q2 2025 | Year ago (Q3 2025) | Q4 2025 | Q1 2026 | Last quarter (Q2 2026) |
|---|---|---|---|---|---|
| Net sales | 167,702 | 180,169 | 213,386 | 181,519 | 200,606 |
| AWS net sales | 30,873 | 33,006 | 35,579 | 37,587 | 42,232 |
| AWS growth from a year earlier, % | 17 | 20 | 24 | 28 | 37 |
| AWS operating income | 10,160 | 11,434 | 12,465 | 14,161 | 16,621 |
| Operating income | 19,171 | 17,422 | 24,977 | 23,852 | 27,461 |
| Cash capex, net | 31,368 | 34,228 | 38,469 | 43,234 | 53,076 |
| Diluted EPS, $ | 1.68 | 1.95 | 1.95 | 2.78 | 5.75 |
Source: Amazon Q2 2025, Q3 2025, Q4 2025, Q1 2026 and Q2 2026 earnings releases and Q2 2026 Form 10-Q. Cash capex is purchases of property and equipment, net of proceeds from sales and incentives.
The Guide Check
Amazon guided third-quarter 2026 net sales to $197.0 billion to $202.0 billion and operating income to $22.5 billion to $26.5 billion.
Net sales: The range implies growth of 9% to 12% from the third quarter of 2025, or nearly 400 basis points more excluding Prime Day, which moved into the second quarter. Reuters reported on Oct. 27 that Amazon's revenue growth is expected to slow to 12.3%, slightly above the top of that range.
Operating income: The guide compares with $17.4 billion in the third quarter of 2025, a figure that included a $2.5 billion Federal Trade Commission settlement and $1.8 billion of estimated severance.
One-offs to strip out: On the company's second-quarter earnings call, CFO Brian Olsavsky said operating income included about $1.2 billion of benefits: about $600 million of tariff refunds and about $600 million, mainly in AWS, from remeasuring energy contracts accounted for as derivatives. The third-quarter guide assumes no impact from energy derivative remeasurements.
AWS: Growth, Margin and Capacity
AWS revenue grew 37% to $42.2 billion in the second quarter of 2026, its fastest growth in 18 quarters, and its operating margin was 39.4%.
Growth: Matching 37% in the third quarter would take about $45.2 billion of revenue, by our math, against $33.0 billion a year earlier. Analysts expect growth of 38.2%, according to Visible Alpha data reported by Reuters.
Margin: The 39.4% margin was up from 32.9% in the second quarter of 2025. By our math, if the full $600 million energy-contract benefit sat in AWS, the margin would have been about 38% without it.
Capacity: CEO Andy Jassy said on the call that Amazon is on track to have "double the power capacity by the end of 2027 that we had in 2025," and that the "lion's share" of 2027 capacity is "largely reserved."
Backlog: Amazon's 10-Q puts commitments not yet recognized in long-term customer contracts, primarily AWS, at about $496 billion, with a weighted-average remaining life of 6.4 years. This year AWS expanded its OpenAI deal by $100.0 billion over eight years and its Anthropic deal by more than $100.0 billion over 10 years.
Capex: The Plan Implies a Bigger Second Half
Amazon's 2026 cash capex plan of about $220 billion implies, by our math, about $62 billion a quarter for the rest of the year, against $53.1 billion in the second quarter.
Jassy raised the plan on the second-quarter call to "approximately $220 billion" from about $200 billion, with "the higher cost of memory" pushing it up. "Even at that amount, we will still not have enough capacity to meet all the demand we have in 2026," he said, and he expects the same in 2027.
That second-half pace rests on $96.3 billion of first-half spending, by our math. Our Hyperscaler Capex Tracker compares Amazon with Microsoft (NASDAQ: MSFT), Alphabet (NASDAQ: GOOGL) and Meta (NASDAQ: META).
Trainium and the Supply Chain
Amazon said in its second-quarter 2026 release that its chips business had passed a $25 billion annual revenue run rate, growing at triple-digit percentages.
Custom silicon: The release said Anthropic and OpenAI made "multi-year, multi-gigawatt commitments" to Trainium. Jassy said there is "a real chance" Amazon will sell Trainium outside its cloud.
Read-across: Trainium shifts some AWS spending toward Amazon's own chips, though Jassy said AWS keeps "a deep partnership with Nvidia" (NASDAQ: NVDA). For memory and storage suppliers, part of the capex increase is higher prices, not more capacity.
What Anthropic's S-1 Shows About Amazon
Anthropic's S-1, filed Oct. 26, 2026, shows a commitment to spend at least $110.0 billion with Amazon from May 2026 to April 2036, and Anthropic convertible notes that Amazon carries at about $97.9 billion.
Anthropic proposes to list on Nasdaq as ANT. Its S-1 also details Amazon's notes, its loan facility and the rest of Anthropic's compute commitments. Our full analysis covers the filing.
The compute deal: Anthropic made the commitment in April, "regardless of actual usage," and pays the difference if it falls short. It can cancel only for Amazon's uncured material breach. The term runs longer than Anthropic's disclosed Google and Microsoft commitments.
The notes: Amazon holds Anthropic convertible notes with $6.2 billion of principal. The S-1 says their rising fair value drove most of Anthropic's $72.4 billion first-half fair-value charge. At the IPO, the notes convert into non-voting Class N shares, capped so that Amazon holds no more than 12% of Anthropic's capitalization unless Amazon waives the cap.
| Amazon's Anthropic holdings, June 30, 2026 | Amount | Basis |
|---|---|---|
| Convertible notes, principal | $6.2B | Anthropic S-1 |
| Notes, Anthropic's liability | $108.6B | Fair value, Anthropic S-1 |
| Notes, Amazon's asset | About $97.9B | Estimated fair value, Amazon 10-Q |
| Unrealized gain on notes in OCI | $92.0B | Amazon 10-Q |
| Non-voting preferred stock | About $92.5B | Carrying amount, Amazon 10-Q |
Source: Anthropic S-1; Amazon Form 10-Q for the quarter ended June 30, 2026. OCI is accumulated other comprehensive income.
The valuation gap: By our math, the two companies value the same notes $10.7 billion apart. Amazon's 10-Q says its methods include "discounts for lack of marketability." Neither filing reconciles the figures.
The facility: Amazon agreed to a facility of up to $20.0 billion, cut to $15.0 billion after it invested $5.0 billion in Anthropic's Series H. The S-1 says amounts become available in $5.0 billion steps as compute capacity milestones are met.
What is still blank: The S-1 leaves Anthropic's aggregate compute commitment as "more than $ ," with no figure. On disclosed amounts, its Broadcom (NASDAQ: AVGO) leases for TPU-based compute, at about $161.2 billion of rent, and its Google commitment, at about $114.5 billion, both exceed its AWS minimum, over different years.
Earnings Per Share: An Investment Story, Not Just AWS
Amazon's second-quarter 2026 net income of $62.6 billion included $53.4 billion of pre-tax other income, "primarily from our investments in Anthropic."
The 10-Q shows a $50.5 billion upward adjustment to Amazon's non-voting Anthropic preferred stock in the quarter, reflecting "observable changes in price related to Anthropic's fundings."
What the $190 billion is: By our math, Amazon carried its Anthropic holdings at about $190 billion on June 30: the notes at about $97.9 billion of estimated fair value, plus the preferred stock at about $92.5 billion. The preferred figure is a carrying amount adjusted for observable price changes, not a full fair-value measure. The sum is not a market value, and neither company reports it.
Why Q3 may differ: The S-1's list of events after June 30 includes no new priced preferred-stock financing. That could mean a much smaller Anthropic gain this quarter, though Amazon decides what counts as an observable price.
At the IPO: The 10-Q says earlier partial note conversions moved gains from OCI into net income: about $3.3 billion in the first half of 2025 and $4.5 billion in the first half of 2026. A conversion at the IPO could do the same with part of the $92.0 billion gain, subject to the 12% cap. Amazon has not said how it will account for it. For comparison, the third quarter of 2025, the year-ago quarter for Thursday's results, included $9.5 billion of pre-tax Anthropic gains.
Cash and Funding
Amazon's free cash flow for the 12 months to June 2026 was an outflow of $7.6 billion, against an inflow of $18.2 billion for the 12 months to June 2025.
Debt: Long-term debt rose to $128.9 billion on June 30 from $65.6 billion at the end of 2025, after $67.0 billion of long-term debt proceeds in the first half. On Sept. 14, Amazon closed £4.25 billion of sterling notes due 2029 to 2045.
OpenAI: The 10-Q says Amazon invested $15.0 billion in OpenAI's Series C preferred stock and committed to buy $35.0 billion more, for $50.0 billion in total. It had invested $28.7 billion by June 30 and funded the remaining $21.3 billion after the quarter ended. That is an investing outflow, not capex, but it competes for the same cash.
Commitments: The 10-Q lists $650.0 billion of total commitments, including $137.2 billion of leases not yet commenced and $130.1 billion of unconditional purchase obligations. The leases line, signed but not started, is a forward signal for developers and landlords.
Peer contrast: Meta launched about $35 billion of stock offerings on Oct. 26. Amazon has so far funded with debt.
The Bull Case and the Bear Case
The bull case for Amazon rests on four straight quarters of faster AWS growth and a $110 billion take-or-pay commitment from Anthropic; the bear case rests on capex running ahead of AWS revenue and earnings that swing on Anthropic marks.
Bull case: AWS growth accelerated in each of the past four quarters, from 17% in the second quarter of 2025 to 37% in the second quarter of 2026, and AWS operating income rose 64% over the same year. Capacity for 2027 is largely reserved, the $496 billion backlog is long-dated, and Anthropic's $110 billion commitment is take-or-pay. An IPO could put a public price on Amazon's Anthropic holdings.
Bear case: Capex has outrun AWS revenue for five quarters, and the plan implies a wider gap unless AWS growth jumps. Both AI contract expansions disclosed this year are with labs that depend on outside funding, and Amazon invests in both. Earnings swing on private-company marks. And on disclosed figures, Anthropic's TPU-linked commitments exceed its AWS commitment.
The Alpha Take
For Amazon's Oct. 29 report, the open question is whether about $62 billion a quarter of capex turns into AWS revenue and margin fast enough to bring free cash flow back.
The second quarter backed Amazon's demand claims with its fastest AWS growth in 18 quarters. Anthropic's S-1 makes the dependency clearer: Amazon is its cloud provider, chip supplier, potential lender and the holder of its non-voting preferred stock and notes. A successful IPO could lift reported earnings through conversion gains, but it would tie more of Amazon's results to one company's share price. Thursday's two lines to separate are AWS operating income and the Anthropic marks.
What to Watch
Amazon holds its third-quarter 2026 call at 5:00 p.m. ET on Thursday, Oct. 29; these are the benchmarks to measure the results against.
Guide: Net sales against $197.0 billion to $202.0 billion and the 12.3% growth Reuters reported analysts expect, and operating income against $22.5 billion to $26.5 billion.
AWS: Growth against 37% in the second quarter and the 38.2% consensus, and operating margin against 39.4%, or about 38% without the full energy-contract benefit.
Capex: Third-quarter spending against the pace of about $62 billion a quarter the plan implies, any change to about $220 billion, the first 2027 signal, and how much of any change is component prices.
Backlog: The 10-Q figure against about $496 billion.
Trainium: Any plan to sell chips outside AWS.
Anthropic: The size of this quarter's gain, how Amazon will account for the IPO conversion, and any comment on the 12% cap.
Funding: Free cash flow, new debt, the $21.3 billion OpenAI payment and the leases-not-yet-commenced line.