Talen, Vistra and Constellation Q3 2026: What Datacenter Contracts Are Worth to Power Producers
All three power producers grew Q3 2026 earnings by 50% or more. None discloses a datacenter contract price. By our math, named datacenter deals cover 8% to 12% of each fleet, and Constellation's own premium range shows what those contracts may be worth.
Talen Energy (NASDAQ: TLN), Vistra (NYSE: VST) and Constellation Energy (NASDAQ: CEG) reported Q3 2026 results on Nov. 3, Nov. 6 and Nov. 9. All three quarters ended Sept. 30, 2026, and all three companies have filed their 10-Qs. Each grew adjusted earnings by 50% or more from a year earlier, helped by acquisitions and higher power and capacity prices.
The three now hold long-term contracts with Amazon (NASDAQ: AMZN), Meta Platforms (NASDAQ: META), Microsoft (NASDAQ: MSFT), Alphabet's (NASDAQ: GOOGL) Google and data center developers. None of the filings gives a price per megawatt-hour for any of those deals. This piece compares what is disclosed with merchant prices and measures how much of each fleet the deals cover. Call quotes are from Motley Fool transcripts.
Talen shares closed at $357.28 on Nov. 3, up 7.3% from $332.99 the day before. Vistra closed at $124.80 on Nov. 6, up 10.6% from $112.89. Constellation closed at $276.09 on Nov. 9, up 10.5% from $249.95. Between the reports, over Nov. 4 and 5, Talen fell 11.5%, Vistra 19.1% and Constellation 9.0%, by our math.
Key numbers
Talen adjusted EBITDA: $669 million in Q3 2026, up 84% from $363 million in Q3 2025.
Vistra adjusted EBITDA: $2.378 billion from ongoing operations in Q3 2026, up 50% from $1.581 billion in Q3 2025.
Constellation adjusted operating EPS: $5.06 in Q3 2026, up 66% from $3.04 in Q3 2025.
PJM West Hub power: averaged $69.97 per MWh in Q3 2026, up 50% from $46.77 in Q3 2025, Constellation's release shows.
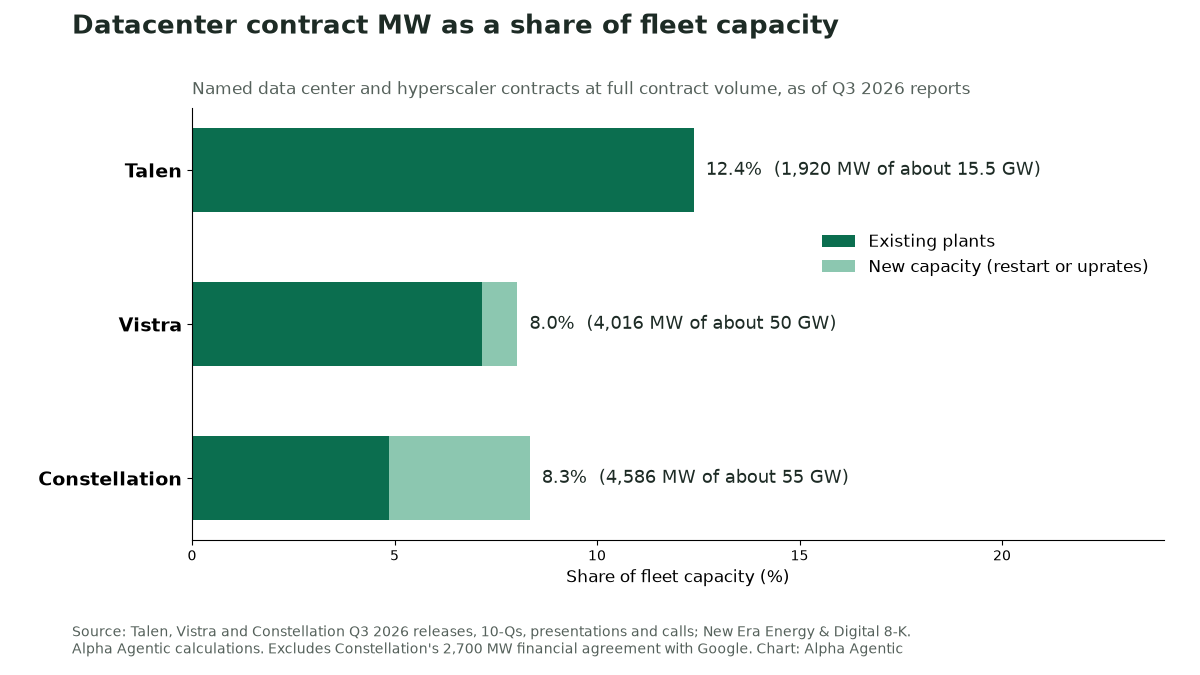
Datacenter contracts: cover 12.4% of Talen's fleet, 8.0% of Vistra's and 8.3% of Constellation's as of the Q3 2026 reports, by our math.
Results Against Last Quarter and Last Year
All three companies posted higher adjusted earnings in Q3 2026 than in Q3 2025 and Q2 2026, and all three raised or narrowed their 2026 guidance.
| Metric | Year-ago quarter (Q3 2025) | Last quarter (Q2 2026) | This quarter (Q3 2026) |
|---|---|---|---|
| Talen adjusted EBITDA | $363M | $374M | $669M |
| Vistra ongoing operations adjusted EBITDA | $1,581M | $1,767M | $2,378M |
| Constellation adjusted operating EPS | $3.04 | $2.55 | $5.06 |
Source: Talen, Vistra and Constellation Q2 and Q3 2026 earnings releases. All figures are non-GAAP.
Talen: Its Q3 release credits acquired plants, higher settled power prices and volumes, and higher capacity revenue, which rose to $323 million from $166 million. GAAP net income fell to $138 million from $207 million on mark-to-market losses on commodity hedges and higher interest from acquisition financing. Talen kept the midpoint of its 2026 adjusted EBITDA guidance and narrowed the range to $2.05 billion to $2.20 billion, from $2.025 billion to $2.225 billion in its Q2 release. It set 2027 at $2.50 billion to $2.85 billion.
Vistra: Its release credits higher realized energy and capacity prices, the plants bought from Lotus and the return of Martin Lake Unit 1. It narrowed 2026 guidance to $7.1 billion to $7.5 billion, from $6.8 billion to $7.6 billion in August. Its first 2027 range, $7.7 billion to $8.5 billion, reflects the Cogentrix plants and the first phase of its Meta contract, its presentation says.
Constellation: Its release credits market and portfolio conditions and the January purchase of Calpine, partly offset by interest costs and lower nuclear tax-credit revenue. Revenue rose to $9.55 billion from $6.57 billion. It raised 2026 guidance to $12.50 to $12.80 a share, from $11.50 to $12.50 in its Q2 release.
What the Contracts Disclose
The three companies have disclosed 10 datacenter-linked contracts with MW and timing as of their Q3 2026 reports, but none of them includes a price.
| Seller and buyer (site) | Contracted MW | Term | Deliveries |
|---|---|---|---|
| Talen to Amazon (Susquehanna) | 1,920 | Through 2042 | Ramping; 840 MW minimum in 2029; full by 2032 |
| Vistra to Amazon Web Services (Comanche Peak) | 1,200 | 20 years, plus up to 20 | From Q4 2027; full by 2032 |
| Vistra to Meta (Perry, Davis-Besse, Beaver Valley) | 2,609, incl. 433 of uprates | 20 years | Partial from late 2026; uprates 2031 to 2034 |
| Vistra to New Era Energy & Digital (Odessa) | 200 to 207 | 20 years | Expected Q3 2027, buyer says |
| Constellation to Microsoft (Crane restart) | About 835 | 20 years | Restart on track for 2H 2027, CEO says |
| Constellation to Meta (Clinton) | 1,121 | 20 years | From June 2027 |
| Constellation to Amazon (Calvert Cliffs) | 690, incl. 190 of uprates | 20 years | Uprates 2030 to 2032 |
| Constellation to Google (11 nuclear units) | About 890 of uprates | 20 years | First uprate 2028 |
| Constellation to CyrusOne (Freestone, Thad Hill) | 380 and 400 | Undisclosed | Undisclosed |
| Constellation to unnamed customer (Peak+) | 270 | 20 years | From 2028 |
Source: company 10-Qs, releases and calls; Talen's June 2025 Amazon release; New Era's Sept. 2026 8-K and release; Constellation's Microsoft, Meta and Amazon releases. Price per MWh is undisclosed for every contract. Excludes Constellation's 2,700 MW, 15-year financial agreement with Google.
Talen: Under the June 2025 deal, Talen supplies Amazon from its Susquehanna nuclear plant. That release said the co-located arrangement would move to a "front-of-the-meter" grid arrangement once transmission work, then expected in spring 2026, was finished. Talen's Q3 release and 10-Q do not say whether that switch has happened, and the 10-Q gives no new contract terms. On the call, CFO Cole Muller said minimum volumes "do ramp to 840 MW in 2029" and that the full ramp takes Talen to "approximately 35% contracted gross margin." CEO Mac McFarland said hyperscalers are "price sensitive."
Vistra: Its 10-Q gives MW, plants and delivery dates for the Amazon and Meta deals. For the Odessa deal, the 8-K filed by the buyer, New Era Energy & Digital (NASDAQ: NUAI), discloses credit support instead of price: a $116 million letter of credit and up to $82.8 million more. New Era's release says the power is expected to be available in Q3 2027. The 8-K says Vistra's obligations depend on conditions that must be met by Dec. 31, 2027.
Constellation: Its 10-Q lists the Amazon, Google and CyrusOne deals and the Microsoft contract at Crane. The Meta Clinton deal is from a 2025 release. On the call, CEO Joseph Dominguez described the Peak+ buyer only as "an investment-grade customer in the data economy market." The release says Peak+ supplies 270 MW from the existing nuclear fleet.
What we count: The table and the fleet shares below leave out four sets of deals. These are Constellation's 2,700 MW financial agreement with Google, which commits no physical capacity, and the 920 MW of nuclear contracts it signed in Q2 2026, including 176 MW with Walmart (NASDAQ: WMT). We also leave out the exclusive 380 MW second phase at CyrusOne's Freestone site and Vistra's 405 MW Pulaski solar contract with Microsoft. Neither company describes the Q2 contracts or the solar deal as data center supply.
Analysis: Contract Prices Against the Merchant Market
Constellation is the only one of the three to publish a price framework, and by our math it implies $69.88 to $99.88 per MWh for new nuclear contracts in 2029.
The framework: Its Q3 presentation lists a 1 GW nuclear contract at a $20 to $50 per MWh premium to the nuclear tax-credit floor as upside for "2029 and beyond." It values that at $125 million to $325 million a year of free cash flow before growth. Dominguez said the range is still "the right sensitivity," adding that the floor "is also going up over time." The deck models that floor at $44.75 per MWh in 2026, rising to $49.88 in 2029. We use the 2029 figure to match the slide's time frame. On the 2026 floor, the band would be $64.75 to $94.75. We also checked the cash value: 1 GW at a 95% capacity factor yields 8.3 TWh a year. At a $20 to $50 premium, that is $166 million to $416 million before tax, or $123 million to $308 million at the deck's 26% tax rate. That is close to the company's range.
Against merchant prices: The presentation puts 2027 forward prices, as of Sept. 30, at $43.59 at Northern Illinois Hub and $76.01 at PJM West. Those are the latest years the deck shows. At Northern Illinois Hub, the low end of the band sits $26.29 above the forward, so a contract in the band would pay well above the market. At PJM West, the forward already sits inside the band, so a contract there mostly buys certainty. Constellation models its existing long-term clean contracts at $70 per MWh in 2026, rising to $88 in 2030. That figure excludes deals signed in 2026.
Vistra and Talen: Neither publishes a premium. Vistra's slides put its expected 2027 realized price, including hedges, at $51.34 per MWh in Texas and $52.69 in the East. Its 10-Q shows ERCOT North Hub power averaged $35.10 in Q3 2026. Talen's 10-Q shows the problem its Amazon deal helps solve. Day-ahead peak power in its PPL zone averaged $58.65 in Q3 2026, $41.86 below PJM West Hub's $100.51. A year earlier the gap was $14.11. Muller said every $5 per MWh improvement in zonal basis is worth about $5 a share of annual adjusted free cash flow.
Our estimate of contract value: Constellation has 1,891 MW of datacenter nuclear contracts on existing plants: Meta, Amazon's 500 MW base and Peak+. If all of it were priced within the company's band, its $125 million to $325 million per GW would imply $236 million to $615 million a year. That is our estimate, not a disclosed value. Constellation does not say where any signed deal falls in the band, and some of that value may already be in its base plan.
Analysis: How Much of Each Fleet Is Spoken For
By our math, named datacenter contracts cover 12.4% of Talen's fleet, 8.0% of Vistra's and 8.3% of Constellation's at full contract volume.
| Company | Datacenter MW contracted | Stated fleet | Share of fleet |
|---|---|---|---|
| Talen | 1,920 | About 15.5 GW | 12.4% |
| Vistra | 4,016 | About 50 GW | 8.0% |
| Constellation | 4,586 | About 55 GW | 8.3% |
Source: company releases, 10-Qs, presentations and the New Era 8-K. Shares are Alpha Agentic calculations and include new capacity from restarts and uprates. Fleets are the companies' round numbers. Vistra's includes Cogentrix, acquired Oct. 30; another Vistra slide says about 49 GW, which would make its share 8.2%. Constellation's 55 GW may include about 4.4 GW of PJM plants it has agreed to sell.
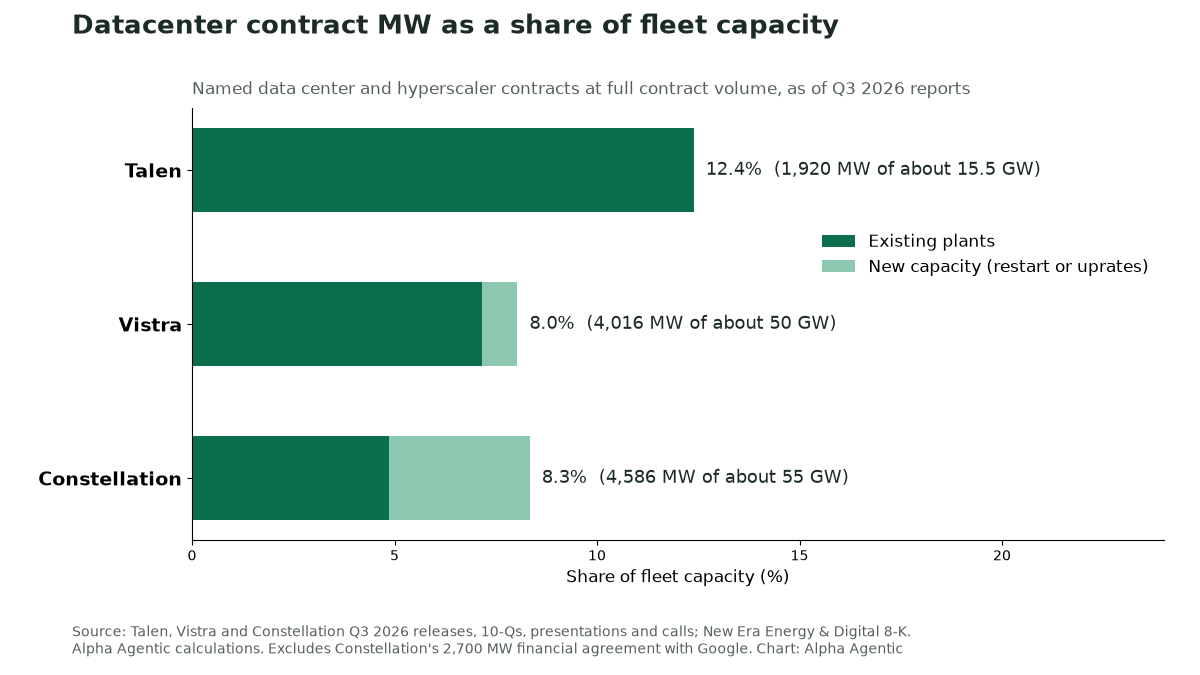
Existing plants versus new megawatts: All of Talen's 1,920 MW comes from an existing plant. Vistra's existing plants supply 3,583 MW, or 7.2% of its fleet, and 433 MW is from future uprates. Constellation's mix differs: 1,915 MW, or 42% of its total, comes from the Crane restart and uprates. Its existing-plant share is 4.9%. Counting the 2,700 MW Google financial agreement would raise Constellation to 13.2%, but that deal does not commit physical capacity.
Concentration: Talen's figure rests on one buyer and one plant. Amazon's 1,920 MW equals about 87% of Talen's 2.2 GW of nuclear capacity, by our math. Vistra has committed 3,376 MW of its 6,448 MW nuclear fleet to Amazon and Meta, or 52%. Stacey Dore, president of Vistra Retail, said on the call that Vistra has not contracted Beaver Valley or "the second part of Comanche Peak."
Timing: Most of these megawatts are not yet flowing. Talen's minimum reaches 840 MW, 5.4% of its fleet, only in 2029. Vistra's Amazon deliveries start in Q4 2027. Constellation's Meta and Crane volumes are due to start in 2027. For now, Q3 2026 earnings came mostly from merchant prices, capacity payments and acquisitions. The contracts mainly add earnings from 2027 onward.
For how this load fits the grid, see our power deep dive. The Hyperscaler Capex Tracker follows the spending behind these buyers.
The Alpha Take
None of the three discloses what a datacenter megawatt-hour sells for. Constellation's $20 to $50 premium framework is the only public yardstick, and our check of its cash math roughly holds. If that range applies, contracts add the most value where merchant prices are weakest, such as Northern Illinois. In PJM West, they mostly trade upside for certainty. Talen relies most on one buyer. If its PPL zone keeps trading far below PJM West, the Amazon deal will carry more of its growth.
What to Watch
PJM capacity auction: Talen President Terry Nutt said most expect the December auction to clear "all the way up to the cap." PJM has proposed that its one-time reliability procurement open March 1, 2027, with results on May 10, 2027, Constellation's 10-Q says.
Unnamed buyer: Constellation said it is withholding the Peak+ customer's name so the customer can announce the deal itself.
First deliveries: Vistra expects partial Meta deliveries from late 2026. Dominguez said Crane remains "on track to restart the plant in the second half of 2027." Constellation's 10-Q notes that some grid upgrades needed for Crane to be fully deliverable could run as late as December 2030, though it has since moved interconnection rights from its Eddystone plant to Crane, a step aimed at reducing them.
More deals: Dore said Vistra is "confident in our ability to execute additional nuclear PPAs." Talen is marketing 300 MW of uncontracted Susquehanna output and 4 GW of powered land.